Mauritius has developed an extensive network of Double Taxation Avoidance Agreements with countries across Africa, Asia, Europe and the Middle East.
These agreements play an important role in facilitating international investment by reducing the risk of double taxation, establishing rules for allocating taxing rights and providing greater certainty to qualifying investors and businesses.
For international businesses, investment holding companies and investment funds, Mauritius may offer a suitable platform for cross-border investment activities, subject to the applicable legal, regulatory and taxation requirements.
A Double Taxation Avoidance Agreement is a bilateral treaty between two jurisdictions that establishes how specified categories of income may be taxed.
Depending on the provisions of the relevant agreement, a DTAA may:
Qualifying recipients may benefit from reduced withholding taxes on dividends, interest and royalties arising in a treaty partner country.
Mauritius can serve as a jurisdiction for investment holding and other cross-border structures where there are genuine commercial reasons for its use.
Treaties establish agreed rules governing taxation between participating countries, reducing uncertainty and potential disputes.
Applicable agreements may provide tax credits, exemptions or other relief mechanisms where income would otherwise be taxed in both jurisdictions.
Treaty provisions may help international businesses understand their tax obligations when conducting activities across different countries.
Establishing a company in Mauritius does not automatically confer entitlement to tax treaty benefits.
The following considerations are particularly important.
An applicant generally needs to establish qualifying tax residence in Mauritius under the relevant treaty.
A Mauritius Tax Residence Certificate may provide important evidence of residence, but does not independently guarantee treaty benefits.
The company's actual management and decision-making arrangements must support its claimed tax residence and comply with applicable requirements.
Where applicable, a Mauritius company must maintain appropriate activities, resources, expenditure and governance arrangements consistent with its business and regulatory obligations.
For certain treaty benefits, including reduced withholding taxes on dividends, interest and royalties, the recipient may need to demonstrate that it is the beneficial owner of the relevant income.
Treaties may contain provisions designed to prevent treaty shopping and other abusive arrangements.
The Principal Purpose Test, where applicable, may restrict benefits if obtaining a treaty advantage was one of the principal purposes of an arrangement and granting the benefit would be inconsistent with the relevant treaty provisions.
Applicants should maintain appropriate accounting records, corporate documentation, tax filings, governance records and supporting evidence of their commercial activities.
A Mauritius Global Business Company may be eligible for treaty benefits where it satisfies the relevant tax residence, regulatory, substance and treaty requirements.
Eligible Mauritius investment funds may benefit from applicable treaties, depending on their legal structure, tax classification, residence and the relevant treaty provisions.
Other entities may potentially qualify where they satisfy the definition of a treaty resident and all applicable conditions.
Authorised Companies, which are generally treated as non-resident for Mauritius income tax purposes, should not be presented as vehicles that ordinarily benefit from Mauritius tax treaties.
London Global Business Solutions Ltd provides corporate establishment, management and administrative services to international businesses, investors and professional intermediaries.
Our services include:
Our objective is to assist clients in establishing and maintaining structures that are commercially appropriate, professionally administered and compliant with applicable legal and regulatory requirements.
Whether you are considering investments into Africa, Asia or other international markets, LGBS can assist you in exploring suitable Mauritius corporate and investment structures.
The following table provides an overview of selected Mauritius tax treaties and the maximum withholding tax rates or exemptions indicated in the Mauritius Revenue Authority's published treaty highlights.
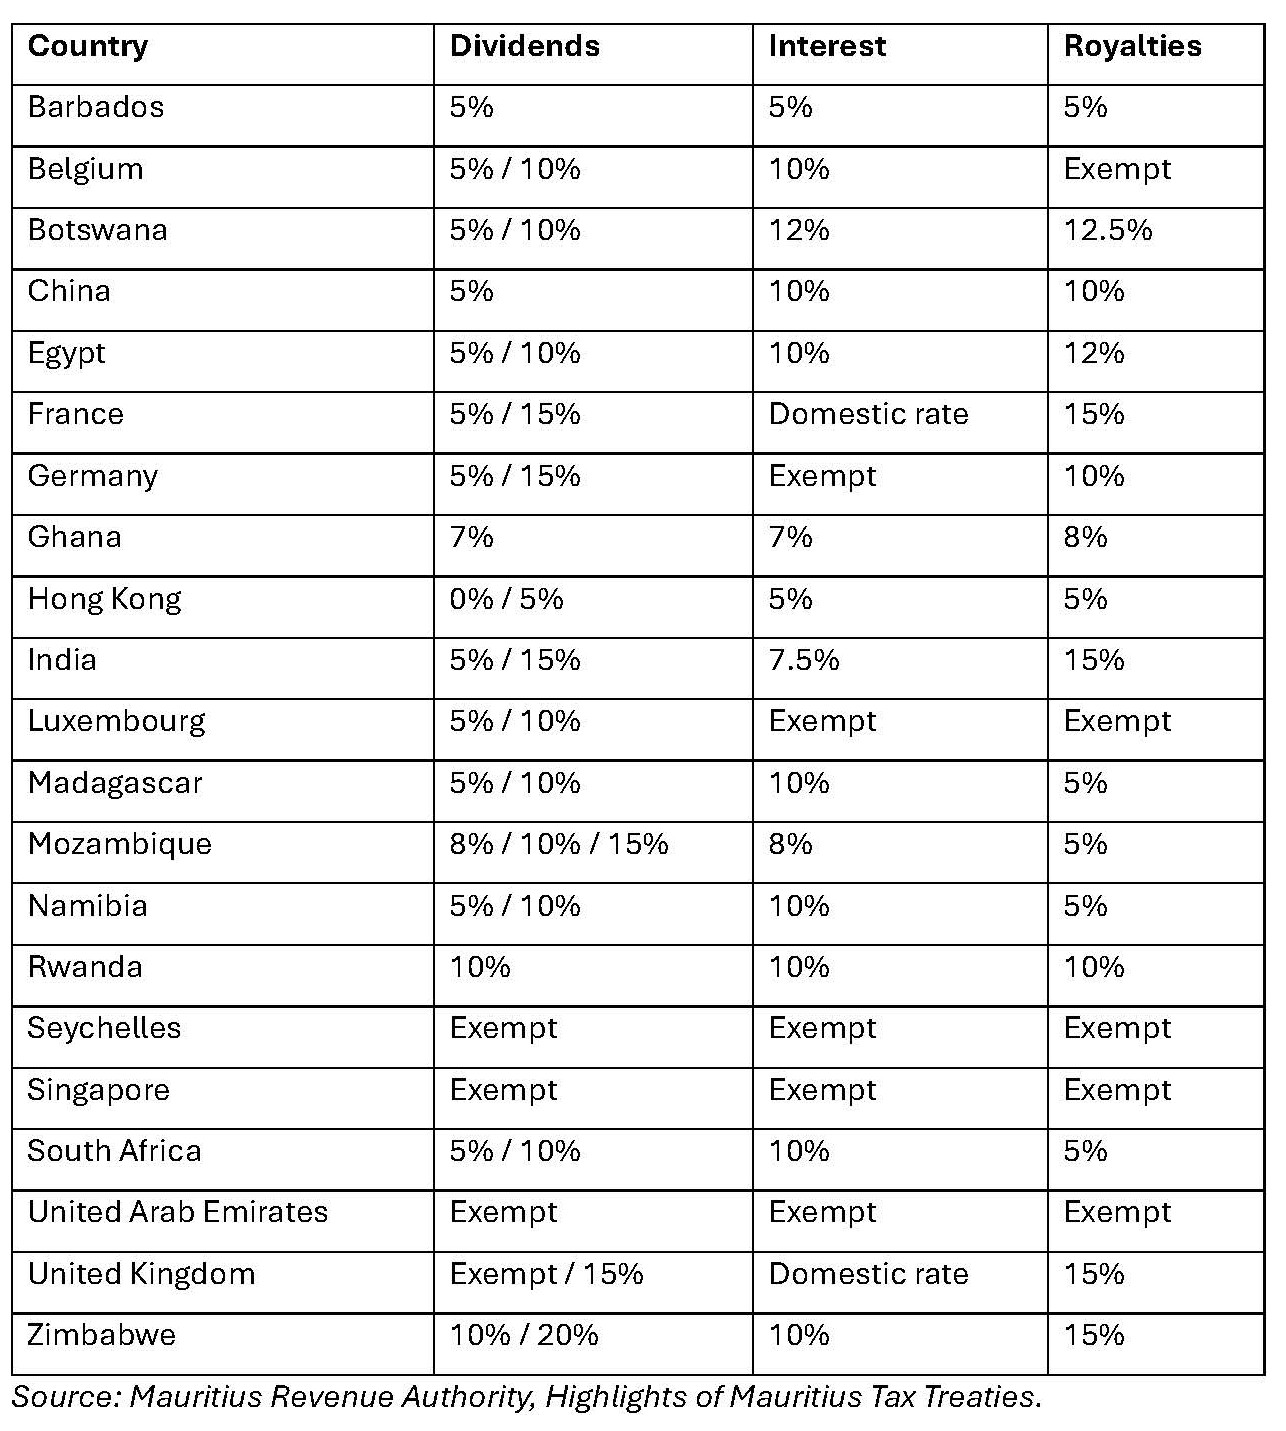
Important: These rates are indicative treaty ceilings or exemptions, not guaranteed tax rates. The applicable rate depends on the specific treaty provisions, eligibility conditions, ownership, type of income and applicable domestic legislation. A treaty rate does not necessarily mean that the source country imposes tax at that rate.For the complete and regularly updated list of treaties, including amendments and protocols, visit the Mauritius Revenue Authority.
Mauritius has established an extensive network of Double Taxation Avoidance Agreements (DTAAs) to facilitate international investment, provide greater certainty in cross-border taxation and reduce the risk of double taxation.
According to the Mauritius Revenue Authority, Mauritius has 45 tax treaties in force, including a partial agreement with Australia.
The tables below provide an overview of the agreements currently in force, their original signature and entry-into-force dates, and the status of additional agreements being developed.
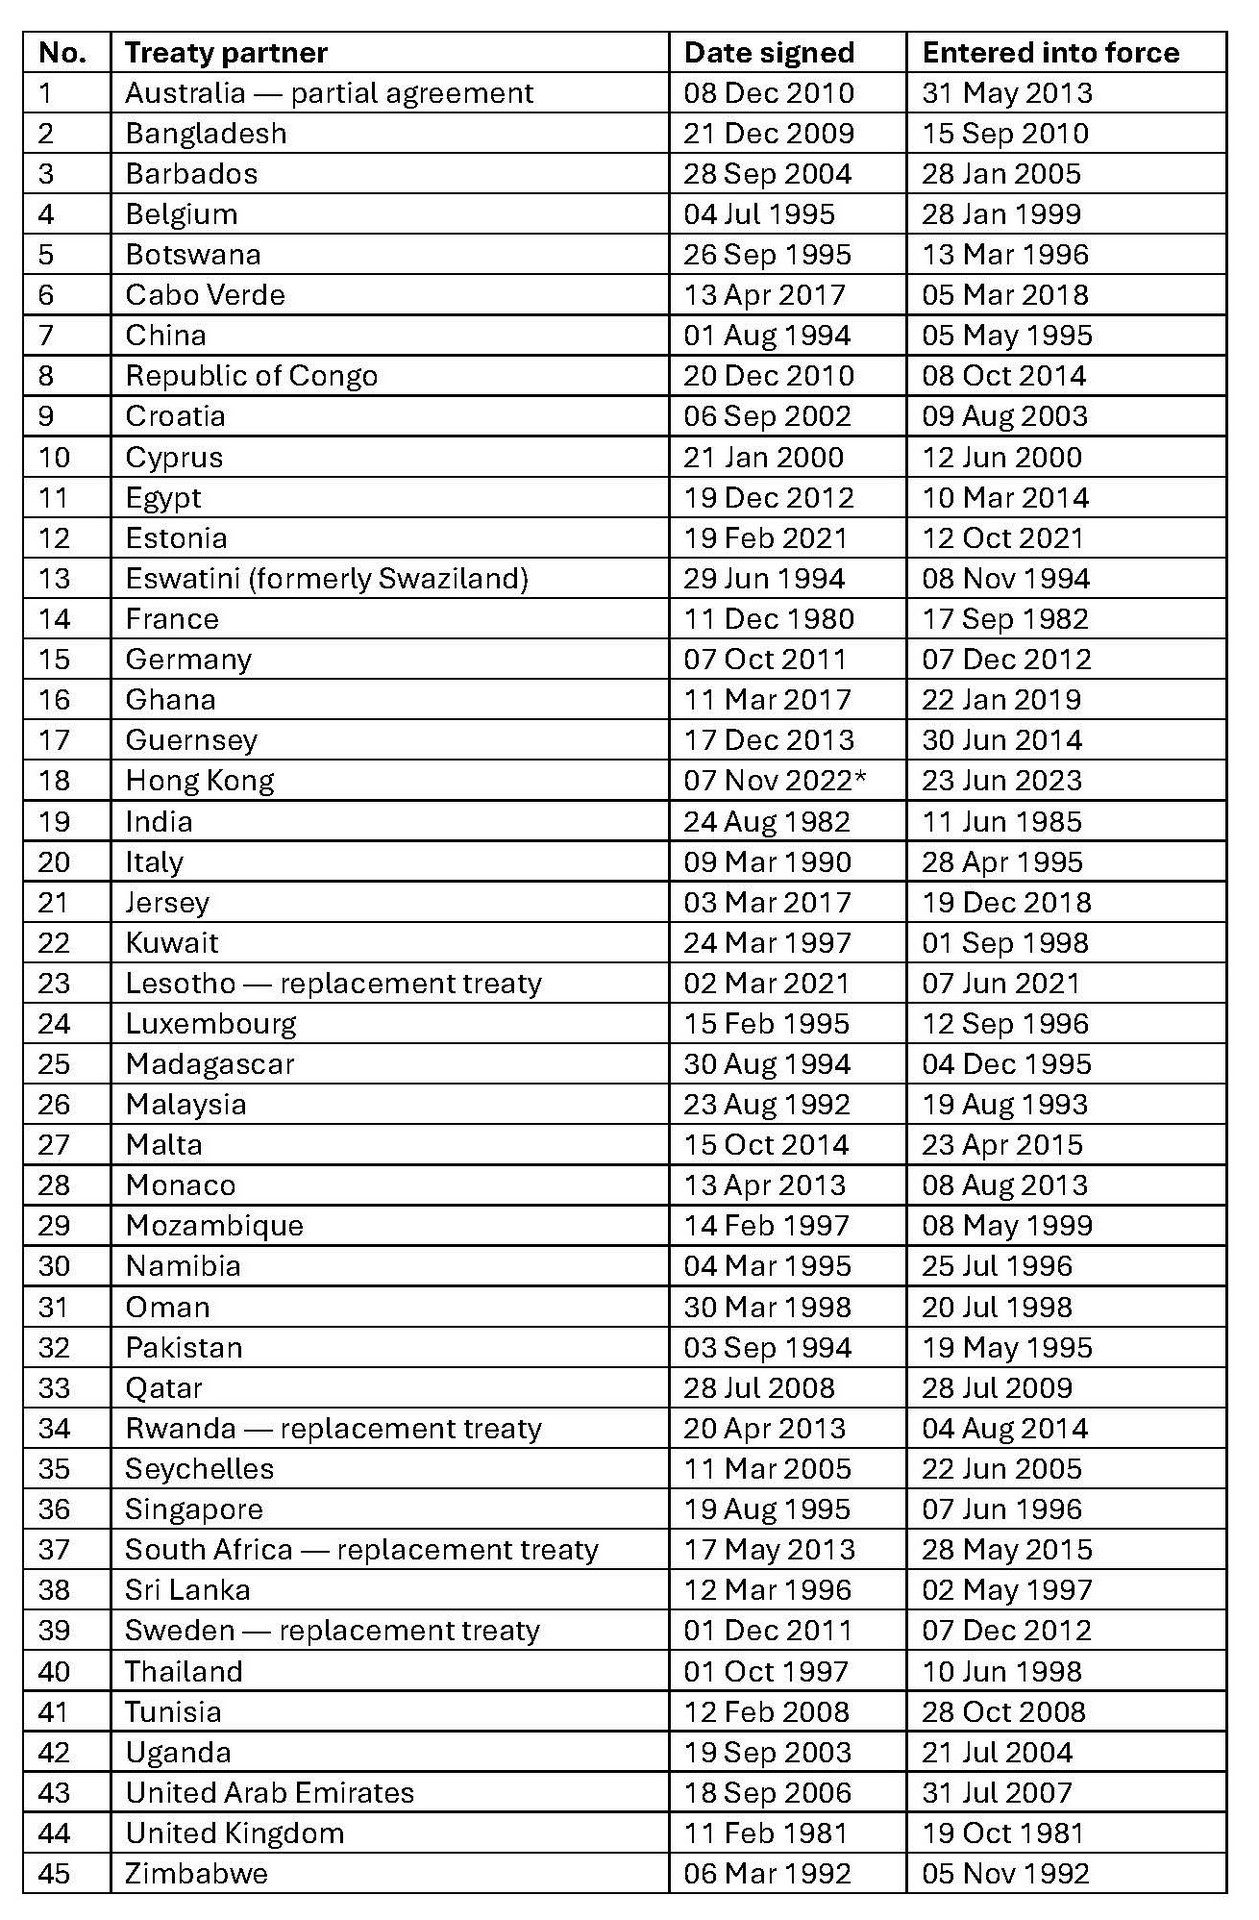
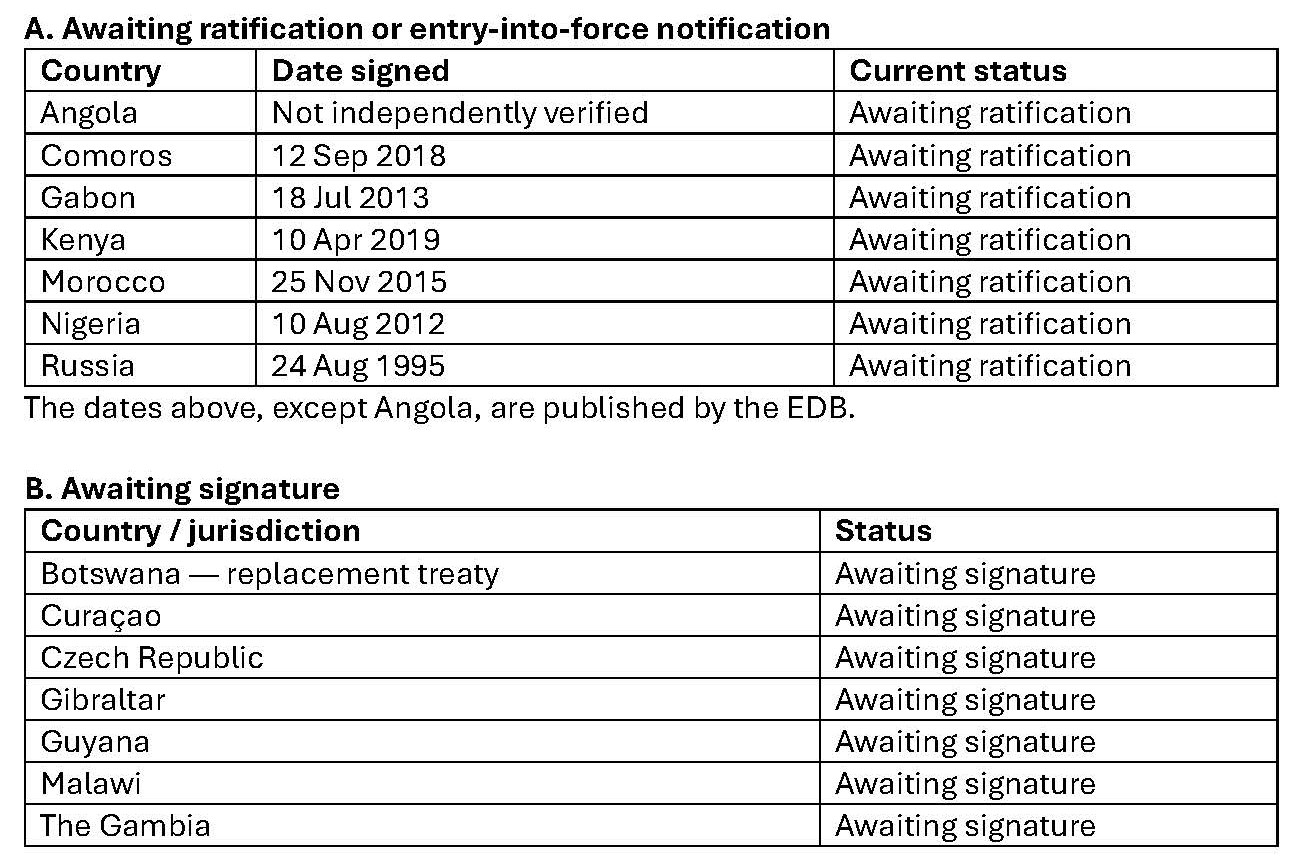
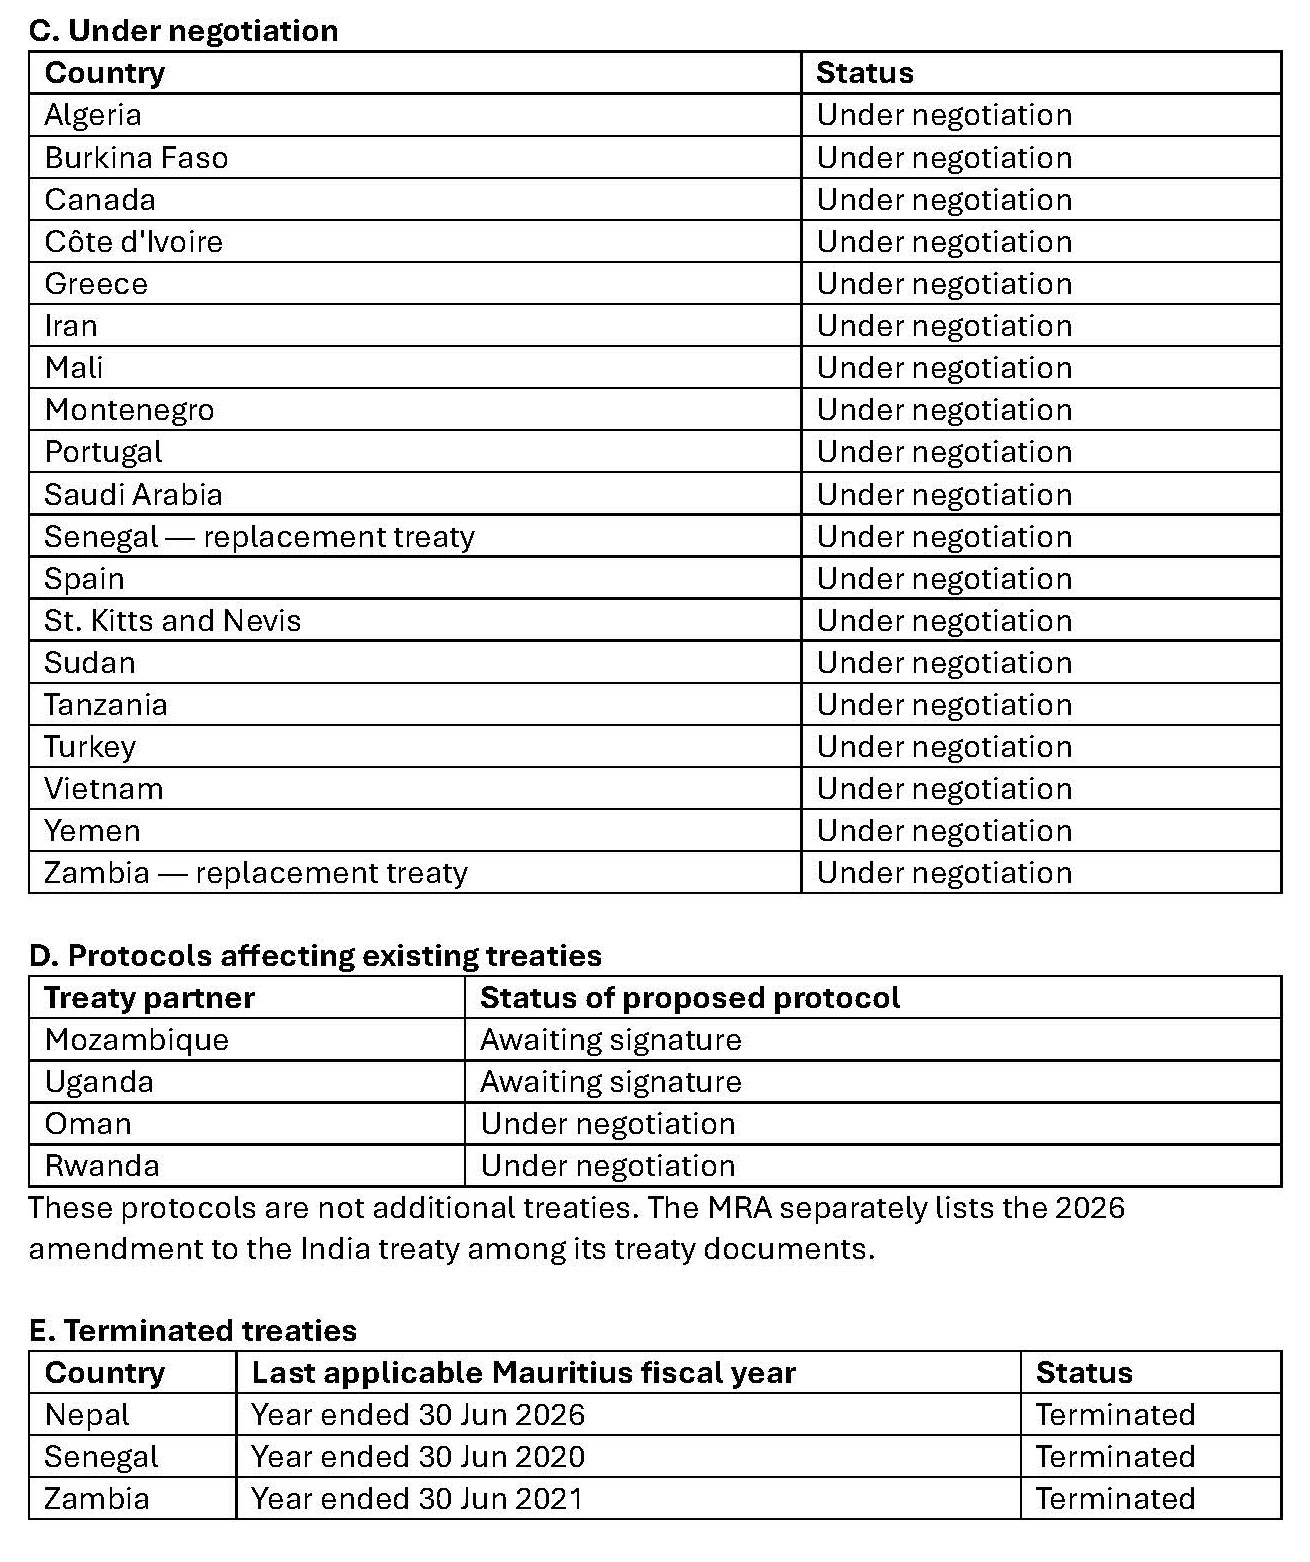
The dates provided refer to the relevant agreements and do not necessarily represent the dates on which particular treaty provisions became effective.
Subsequent protocols, the Multilateral Instrument and changes in domestic legislation may affect the application of individual agreements.
The existence of a treaty does not automatically confer treaty benefits on a Mauritius company or other entity. Eligibility depends on the relevant treaty provisions, tax residence, beneficial ownership, economic substance, anti-abuse requirements and other applicable conditions.
Agreements awaiting ratification, signature or negotiation are not operative tax treaties.
Official source: Mauritius Revenue Authority — Double Taxation Avoidance Agreementshttps://www.mra.mu/taxes-duties/international-taxation/double-taxation-agreements
Information reviewed on 24 October 2026. Readers should consult the official treaty instruments and the Mauritius Revenue Authority for subsequent amendments and changes in status.